analytics Executive Research Summary Matrix
Q1 2024 VINTAGEKey Thesis: The Federal Open Market Committee's Summary of Economic Projections reveals an institutional reluctance to rapidly loosen monetary conditions, driven by persistent service-sector wage inertia and an upward drift in the structural real equilibrium rate ($r^*$). Market expectations continue to underestimate terminal duration and upside inflation tail risks.
Deconstructing the Summary of Economic Projections (SEP) & Dot Mechanics
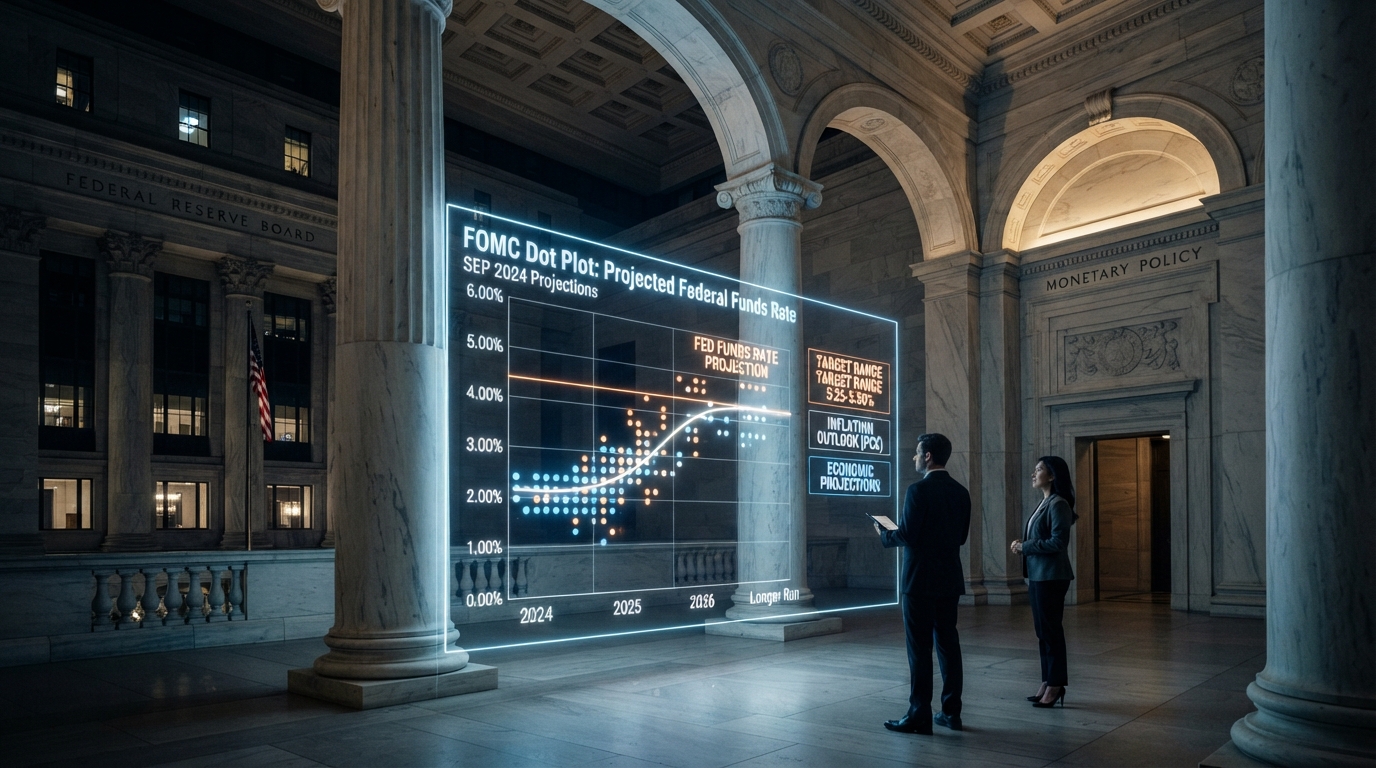
The Federal Open Market Committee’s (FOMC) “Dot Plot,” formally embedded within the quarterly Summary of Economic Projections (SEP) released in March, June, September, and December, functions as the central communication apparatus for Federal Reserve forward guidance. Each individual dot represents the personal, non-attributable assessment of appropriate monetary policy by each of the 19 Federal Reserve policymakers—comprising the seven members of the Board of Governors in Washington, D.C., and the 12 Federal Reserve Bank presidents.
A pervasive misconception across financial journalism is that all 19 dots correspond to current voting members. Under the rotating architecture of the Federal Reserve Act, only 12 policymakers vote on policy at any given meeting: the seven Governors, the president of the New York Fed (permanent vice chair), and four regional bank presidents on rotating one-year cycles. However, all 19 policymakers submit dots regardless of current voting status. Consequently, seven non-voting participants contribute equally to the median, creating a unique institutional dispersion where regional hawks and doves influence the visual trajectory without holding a direct vote at the immediate discount window or federal funds target vote.
info Dot Mechanics & Anonymity Protocol
Every participant submits their modal projection—the single trajectory they consider most likely to foster price stability (2% PCE) and maximum sustainable employment—predicated on their idiosyncratic assumptions regarding exogenous fiscal impulse, global productivity shocks, and labor participation rates. Crucially, the dots do not represent a committee commitment or binding contract; they are an aggregation of independent baseline forecasts under zero collective bargaining.
The Elusive Neutral Rate: Deconstructing r-Star (r*) Drift
At the epicenter of current macroeconomic debates sits the structural drift of the neutral rate of interest—conceptually denoted as $r^*$ (r-star). This represents the theoretical real interest rate at which monetary policy is neither expansionary nor restrictive, holding aggregate demand at full potential output with constant 2% inflation. Because $r^*$ is unobservable, economists estimate it using Laubach-Williams, Holston-Laubach-Williams, and Hamilton-Zeldes statistical filter models.
Throughout the post-GFC decade (2010–2020), the Fed's median longer-run dot steadily fell from 4.25% down to an anchored 2.50%, implying an $r^*$ of merely 0.50% when subtracting the 2.0% core PCE inflation target. However, current post-pandemic dynamics have driven substantial upward re-evaluations:
Structural US federal deficits averaging 6-7% of GDP absorb global savings, requiring higher real yields to clear sovereign debt auctions.
Artificial intelligence hardware, reshoring of supply chains, and green energy infrastructure demand massive capital expenditures, raising the marginal return on capital.
Nearshoring and fragmented international commerce diminish the disinflationary tailwinds once exerted by frictionless global labor arbitrage.
In recent SEP iterations, participants have begun incrementally lifting the longer-run dot upwards from 2.50% toward 2.875% and 3.25%. A permanent shift of just 50 basis points in the structural neutral rate radically alters terminal equity discount rates, commercial real estate cap rates, and the entire architecture of perpetual corporate bond refinancings.
Market Pricing vs. FOMC Guidance: Unpacking the Divergence
Historically, public markets have rarely taken the FOMC's median dot plot at face value. A perpetual friction exists between the institutional forward projections published in the SEP and market-implied pricing derived from 30-Day Federal Funds futures contracts and Secured Overnight Financing Rate (SOFR) strip options.
Why do markets repeatedly "fight the Fed"? The structural explanation lies in asymmetric loss functions. Fixed income derivatives traders trade economic probability distributions rather than pure baseline modes. If markets assign even a 20% risk of an acute liquidity freeze, credit crisis, or recessionary shock, the option-implied expected value of the rate curve drops considerably below the Fed's modal dot plot, which assumes an uninterrupted glide path toward equilibrium.
Historical Dot Plot Accuracy: A 12-Year Retrospective Scorecard
Introduced under Chairman Ben Bernanke in January 2012 as an instrument of enhanced transparency, the Dot Plot's empirical track record over the past 12 years has demonstrated both tactical usefulness and substantial structural forecasting errors:
The 2014–2016 Over-Optimism Cycle
Between 2014 and 2016, FOMC dots consistently signaled four 25-bps rate hikes per calendar year. In reality, persistent European sovereign debt crises, Chinese currency devaluations, and energy price collapses caused the Fed to execute merely one hike in 2015 and one in 2016. The dots overestimated actual rate tightening by more than 200 basis points.
The 2021 “Transitory” Inflation Error
In March 2021, the median dot plot signaled near-zero interest rates through the end of 2023. By late 2022 and early 2023, the Fed was forced into the most aggressive synchronized tightening cycle in four decades, taking the benchmark rate past 5.25%. The 2-year forecast missed realized rates by over 500 basis points—the largest divergence in Federal Reserve history.
The 2018 Rate Plateau & 2023 Hawkish Hold Guidance
Conversely, the Dot Plot successfully anchored intermediate expectations during the 2018 tightening cycle and the 2023 "higher-for-longer" transition, preventing premature market easing and signaling resolute monetary policy during core PCE stabilization phases.
Comprehensive Institutional Rate Cycle Matrix
To translate abstract dot plot dispersion into actionable macro modeling, our strategy desk has synthesized the four primary macroeconomic trajectories for the next 24 months:
| Scenario Path | Median Dot | 10Y UST Range | Equity Multiple Impact | USD Index (DXY) | Duration Stance |
|---|---|---|---|---|---|
| Hawkish Drift (Sticky Core PCE) | 5.125% - 5.375% | 4.40% – 4.75% | Multiple compression (-8% to -12%) | Bullish (106.0 – 108.5) | Underweight (< 3.5 yrs) |
| Base Case (PCE Glide Path) | 4.375% - 4.625% | 3.90% – 4.25% | Multiple stability (19x–21x NTM) | Rangebound (102.5 – 104.5) | Neutral (5.0 – 6.5 yrs) |
| Accelerated Easing (Disinflation) | 3.625% - 3.875% | 3.40% – 3.75% | Multiple expansion (+10% to +14%) | Bearish (99.0 – 101.5) | Overweight (7.0 – 10.0 yrs) |
| Hard Landing (Exogenous Shock) | < 3.000% | 2.75% – 3.20% | EPS degradation dominates multiples | Initial Spike (Liquidity Safe Haven) | Max Long Duration (> 12 yrs) |
Quantitative Transmission Channels: Fixed Income, Equities, & FX
Monetary policy dot signals transmit into real financial assets through three primary mechanisms: term premium re-anchoring, corporate discount cash flows, and global currency arbitrage.
When SEP dots shift upward in outer years, the short end of the yield curve (2Y UST) anchors firmly, forcing duration adjustments onto the long end (10Y and 30Y UST). This triggers a "bear steepener" dynamic where long-dated paper falls in price as investors demand greater term premia to hold duration against elevated supply risks.
Long-duration growth equities—specifically software and mega-cap semiconductor enterprises whose intrinsic values rely heavily on cash flows 7 to 15 years in the future—exhibit high convexity to the Fed's terminal rate. A 50-bps sustained upward shift in $r^*$ reduces DCF enterprise value multiples by approximately 7.2% across high-multiple cohorts.
Furthermore, the FX transmission channel operates via uncovered interest parity (UIP). A wider spread between the Fed's projected rate trajectory and the European Central Bank (ECB) or Bank of Japan (BOJ) policy curves sustains persistent dollar liquidity strength, tightening financial conditions in emerging market economies with dollar-denominated sovereign liabilities.
Institutional Portfolio Rebalancing Playbook
In light of higher-for-longer dot plot geometry and upward neutral rate adjustments, institutional asset managers are executing a four-part tactical rotation:
Cash Sweeps & Ultra-Short Duration Lock-in
Transition out of overnight sweep accounts into 6- to 12-month Treasury bills to lock in terminal yields before early rate cuts compress short paper from 5.3% toward 4.5%.
Intermediate Belly Laddering (3Y–7Y)
Avoid extreme barbell exposures. The intermediate "belly" of the curve provides optimal roll-down return and capital preservation if the Fed maintains restrictive rates longer than index benchmarks anticipate.
High-Quality Floating Rate Credit Over High Yield
With high-yield credit spreads hovering near historical tight percentiles (sub-350 bps OAS), investors are uncompensated for default tail risks. Prioritize AAA-rated Collateralized Loan Obligations (CLOs) and senior floating-rate notes.
Dividend Aristocrats & Free Cash Flow Yielders
In equity allocations, prioritize companies with net-cash balance sheets and high Return on Invested Capital (ROIC) that generate internal funding without needing secondary debt capital markets at elevated coupon rates.
Frequently Asked Questions
Key educational questions regarding the FOMC Dot Plot, monetary mechanics, and investor interpretation:
1. What exactly is the Fed Dot Plot and who gets to vote on it? expand_more
2. Why do financial markets often disagree with the SEP dots? expand_more
3. How does the neutral rate (r*) impact 30-year mortgages and long-term bonds? expand_more
4. What is the difference between the headline SEP projections and FOMC minutes? expand_more
5. How should retail investors interpret dot plot shifts without overreacting? expand_more
Executive Synthesis & 5 Core Decision Rules for Macro Allocation
Respect the Longer-Run Drift: As long as the longer-run median dot drifts upward, treat fixed income yields above 4.5% as structural value rather than temporary cyclical anomalies.
Beware the Asymmetric Fed Cut Bet: Do not front-run aggressive rate cuts based purely on market sentiment until monthly Core PCE annualized run-rates decisively print below 2.4%.
Manage Convexity Over Duration: Prioritize 5-year benchmark maturities where the combination of high reinvestment yield and moderate price sensitivity shields portfolios from bear-steepening surprises.
De-Lever Debt-Sensitive Equities: Scrutinize leveraged balance sheets. Companies dependent on refinancing high debt loads between 2024 and 2026 will face steep net margin compression.
Use Dot Dispersion as a Volatility Gauge: Wide dispersion among dots (e.g. >75 bps) implies elevated policy disagreement and higher future rate volatility—warranting disciplined stop-losses and option hedges.