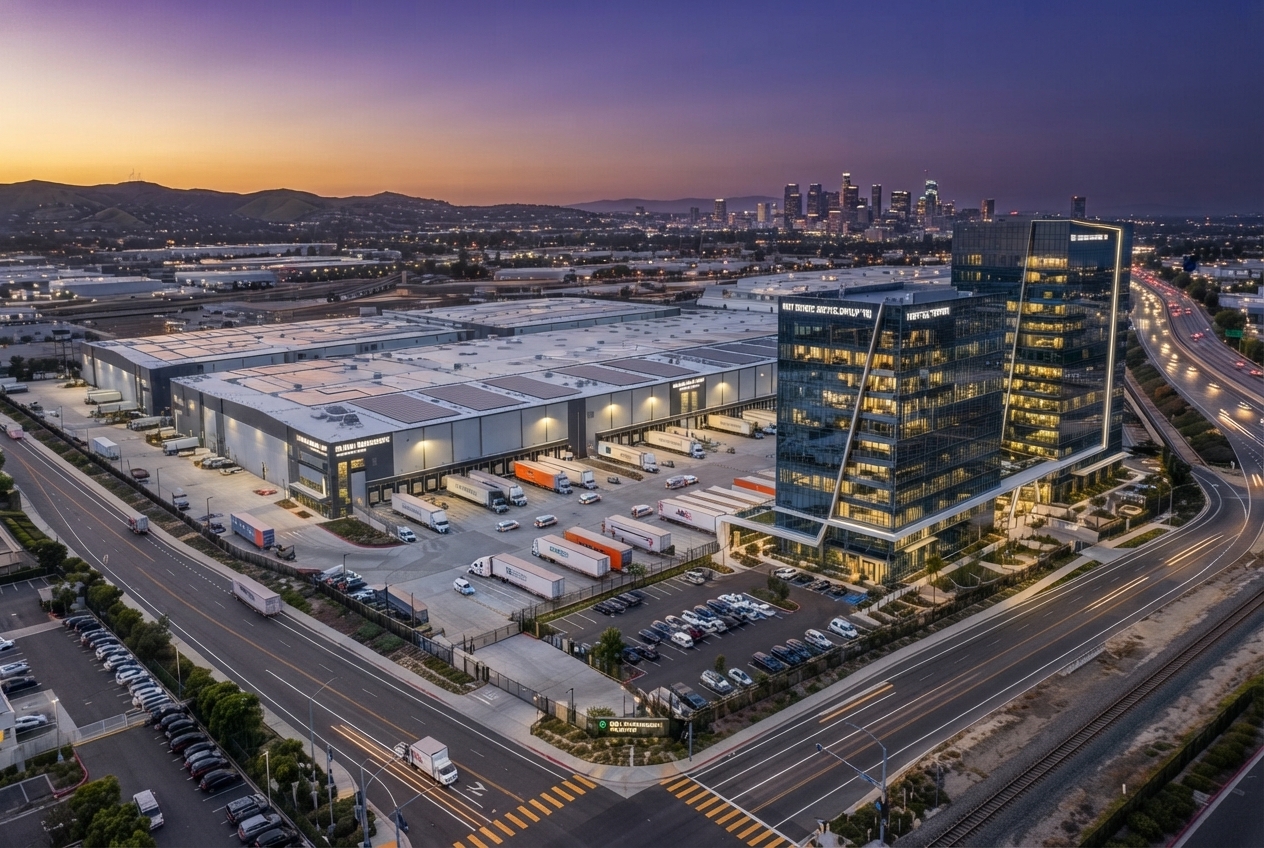
Over the past two decades, commercial real estate portfolios have experienced a structural re-pricing. Once categorized as low-margin, unglamorous manufacturing sheds and bulk storage facilities, industrial real estate has emerged as the foundational operating backbone of global consumer economies and corporate logistics. The modern industrial Real Estate Investment Trust (REIT) does not merely own warehouse space; it owns mission-critical digital connectivity nodes, automated fulfillment hubs, and electrified inventory depots indispensable to multinational trade.
Unlike discretionary retail storefronts vulnerable to digital displacement or suburban office campuses navigating permanent telecommuting patterns, industrial REIT assets benefit from persistent, inelastic secular demand. Understanding how to evaluate these specialized equity REITs requires mastering the financial nuances of triple-net (NNN) contractual leases, synthetic rental escalators, replacement cost economics, and specialized valuation yardsticks including Funds From Operations (FFO) and Adjusted Funds From Operations (AFFO).
The Macro Structural Shift: Why Industrial Outperformed Office and Retail
The capital reallocation toward industrial REITs is rooted in three distinct secular macro tailwinds: exponential digital commerce penetration, systemic supply chain redundancy policies, and domestic re-industrialization initiatives.
The E-Commerce Space Multiplier
Empirical data from major logistics operators indicates that pure-play e-commerce fulfillment operations require approximately three times the square footage of conventional brick-and-mortar logistics networks. Online retail demands extensive staging space for reverse logistics (product returns), expansive multi-tier racking systems, automated picking paths, and larger employee break areas. Every incremental $1 billion in global online retail sales historically translates into roughly 1 to 1.2 million square feet of incremental warehouse demand.
From Just-in-Time (JIT) to Just-in-Case (JIC)
The supply chain disruptions of the early 2020s exposed critical vulnerabilities in lean, just-in-time inventory paradigms. Global enterprises experienced crippling stockouts, catastrophic freight fee surges, and compromised brand equity. Consequently, corporate treasuries and supply officers shifted toward holding strategic safety stock inventories. Maintaining a permanent buffer of 5% to 10% in excess warehouse capacity across domestic hubs created a systemic, multi-year floor under national occupancy rates.
Reshoring and Nearshoring Waves
Legislative actions such as the U.S. CHIPS and Science Act, the Inflation Reduction Act, and heightened geopolitical friction have incentivized massive capital expenditures into domestic manufacturing. Battery gigafactories, semiconductor fabrication facilities, and advanced automotive assembly plants generate ancillary demand for regional suppliers, tier-one parts distributors, and raw materials warehousing within immediate transit radiuses.
E-commerce operations require dramatically larger floor plates due to sorting complexity and return velocity.
Financial Anatomy of Industrial Leases: The Power of Triple-Net (NNN)
The structural defensive moat of industrial REITs lies within their contractual lease structure. The overwhelming majority of Class-A industrial properties operate under Triple-Net (NNN) agreements. In this configuration, the tenant agrees to pay a base rental rate while directly absorbing the three major operating expense categories of real estate:
The tenant absorbs all municipal, county, and state real property assessments, shielding REIT bottom lines from reassessment cycles.
All casualty, hazard, and liability insurance premiums are remitted directly by the occupier, insulating landlords from rising climate premiums.
Routine upkeep, HVAC maintenance, parking lot surfacing, and operational expenses are fully tenant obligations.
Contractual Rent Escalators and Inflation Protection
Unlike multifamily residential REITs that reset leases annually, industrial leases feature longer maturities—typically ranging between 5 to 15 years. However, industrial contracts routinely include embedded contractual rent escalators. Historically fixed at 2.0% to 2.5% annually, recent contracts increasingly feature compound annual step-ups of 3.5% to 4.5% or explicit CPI-linked adjustments with defined caps and collars.
Furthermore, the Weighted Average Lease Term (WALT) serves as a vital risk metric. A longer WALT provides high revenue certainty, while a staggered expiration schedule in a supply-constrained infill market enables landlords to recapture "loss-to-lease"—marking below-market older rents up by 20% to 60% upon lease rollover.
Deconstructing REIT Valuation: Why Net Income Fails & How to Model FFO, AFFO, and NAV
Standard GAAP accounting net income is fundamentally flawed when assessing real estate investment trusts. Under GAAP conventions, physical real estate assets must be depreciated on a straight-line schedule over 27.5 to 39 years. However, well-maintained industrial properties in strategic infill locations virtually always appreciate over time or sustain robust residual economic value. Consequently, GAAP net income grossly distorts cash-generating capacity.
NAREIT Standard Metric
Funds From Operations (FFO)
By adding back non-cash real estate depreciation and eliminating non-recurring gains on property liquidations, FFO provides an apples-to-apples operating baseline across the entire sector.
True Economic Cash Flow
Adjusted FFO (AFFO)
AFFO represents true free cash flow available to fund common distributions. It factors out paper straight-line rent accounting and subtracts recurring tenant improvements and roof replacements.
Cap Rates and Net Asset Value (NAV) Spreads
REIT analysts routinely evaluate industrial REITs by benchmarking their public market enterprise value against private market Net Asset Value (NAV). The underlying asset value is derived by dividing 12-month forward Net Operating Income (NOI) by market Capitalization Rates (Cap Rates):
When a high-quality industrial REIT trades at a 15% discount to NAV, public equity markets are valuing the real estate at a lower price per square foot than private sovereign wealth funds and institutional buyers are willing to pay. Conversely, a sustained premium to NAV provides the REIT's management team with a low cost of equity capital, allowing them to issue accretive secondary stock offerings to acquire yield-expanding properties.
Industrial REIT Sub-Sectors & Comprehensive Evaluation Matrix
The industrial real estate ecosystem is not monolithic. Asset classes vary substantially in capital expenditure requirements, lease terms, geographical scarcity, and sensitivity to broader economic cycles.
| Sub-Sector Classification | Cap Rate Range | Typical WALT | Clear Height | Replacement Cost Sensitivity | Primary Demand Driver |
|---|---|---|---|---|---|
| Pure-Play Last-Mile Infill e.g., Rexford, Prologis Urban | 4.2% – 5.1% | 4 – 7 Years | 24′ – 32′ | Extreme (Land scarcity) | Same-day e-commerce delivery |
| Regional Big-Box Distribution e.g., First Industrial, Duke (merged) | 5.2% – 6.3% | 7 – 12 Years | 36′ – 42’+ | Moderate (Land available in exurbs) | National multi-state staging hubs |
| Cold Storage & Food Infrastructure e.g., Americold, Lineage | 5.8% – 7.1% | 10 – 18 Years | 40′ – 55′ | Very High (Refrigeration CapEx) | Grocers, perishable supply chains |
| Flex Industrial / Advanced Tech Hubs e.g., STAG Industrial, EastGroup | 5.5% – 6.6% | 5 – 8 Years | 18′ – 26′ | Moderate (Office/industrial blends) | Light assembly, EV & robotics suppliers |
Note: Cap rates reflect normalized Tier-1 and Tier-2 asset transactions. Source: TFT Quantitative Portfolio Analysis.
Navigating Supply Waves, Interest Rate Sensitivity, and Power Constraints
The Post-2022 Speculative Construction Digestion
Between 2021 and 2023, developers responded to pandemic warehouse shortages by launching historically unprecedented construction pipelines. As debt capital was cheap, speculative ground-breakings soared across high-growth Sunbelt markets (Phoenix, Dallas-Fort Worth, Atlanta, Inland Empire East). As interest rates escalated in 2023–2024, institutional tenants paused capital expenditures, leading to a temporary surge in vacancy rates to approximately 6.2% nationally.
However, high interest rates created their own cure: new construction starts dropped by over 65% from peak levels. Infill coastal markets (Southern California, Northern New Jersey, Miami) experienced virtually zero supply additions due to strict municipal zoning hurdles, environmental permits, and finite developable land parcels.
The Hidden Moat: Power Substation Capacity
The most under-appreciated moat in modern industrial real estate is electrical utility infrastructure. Traditional manual warehouses operated with modest electrical connections of 400 to 800 amps. Modern logistics centers operating automated Autonomous Guided Vehicles (AGVs), multi-level conveyor sortation systems, and EV freight charging stations require 3,000 to 8,000+ amps.
With regional electrical grid operators facing queue delays of 3 to 6 years for substation transformers, existing Class-A facilities with secured high-voltage feeds possess significant pricing power that cannot be quickly replicated by speculative builders.
Strategic Allocation Framework: Building an Industrial REIT Allocation
When incorporating industrial REITs into a diversified wealth management framework, investors should evaluate potential holdings across three primary balance sheet filters:
1. Fixed-Rate Debt Duration & Maturities
Examine the balance sheet's exposure to floating-rate debt. Premier operators maintain >85% of their total debt in fixed-rate, unsecured senior notes with a weighted maturity profile exceeding 6 to 8 years. This structure insulates earnings from short-term Federal Reserve rate volatility.
2. AFFO Payout Ratio Safety Threshold
Avoid seeking high nominal yields from REITs running an AFFO dividend payout ratio above 85%. Blue-chip industrial REITs consistently target a conservative payout ratio between 65% and 75% of AFFO. This intentional buffer retains capital to fund property developments and protects the dividend during downturns.
3. Re-leasing Spread Momentum
Track the quarterly "cash rent change" on expiring leases. Infill industrial REITs with massive embedded rent marks continue to report cash re-leasing spreads between 25% and 45%, providing predictable, organic same-store Net Operating Income (SSNOI) expansion regardless of macro GDP fluctuations.
Frequently Asked Questions
What is the fundamental difference between equity REITs and mortgage REITs (mREITs)?
How do interest rate hikes and Federal Reserve policy impact industrial REIT valuations?
Are industrial REIT dividends taxed as ordinary income or qualified dividends?
How does North American nearshoring impact warehouse demand along trade corridors?
What are the primary warning signs of an unsustainable REIT dividend cut?
fact_check
Executive Synthesis & Key Takeaways
Executive Synthesis & Key Takeaways
Mission-Critical Moats
Industrial assets operate as vital logistics nodes where tenant relocation friction and inventory downtime far exceed annual rent escalations.
AFFO is King
Always analyze dividend safety and valuation multiples using Adjusted Funds From Operations, eliminating deceptive non-cash GAAP depreciation.
The Power Grid Barrier
Multi-megawatt electrical substation capacity and regional transformer scarcity provide premier infill warehouses with durable pricing advantages.
Infill vs. Sunbelt Supply
Coastal infill logistics hubs possess natural geographic and zoning boundaries, insulating them from the supply digestion seen in unzoned exurbs.
Tax Efficiency Strategy
Hold high-yielding industrial REIT shares inside tax-advantaged accounts (Roth/Traditional IRAs or 401ks) to mitigate ordinary income tax drag and compound cash distributions unimpeded.