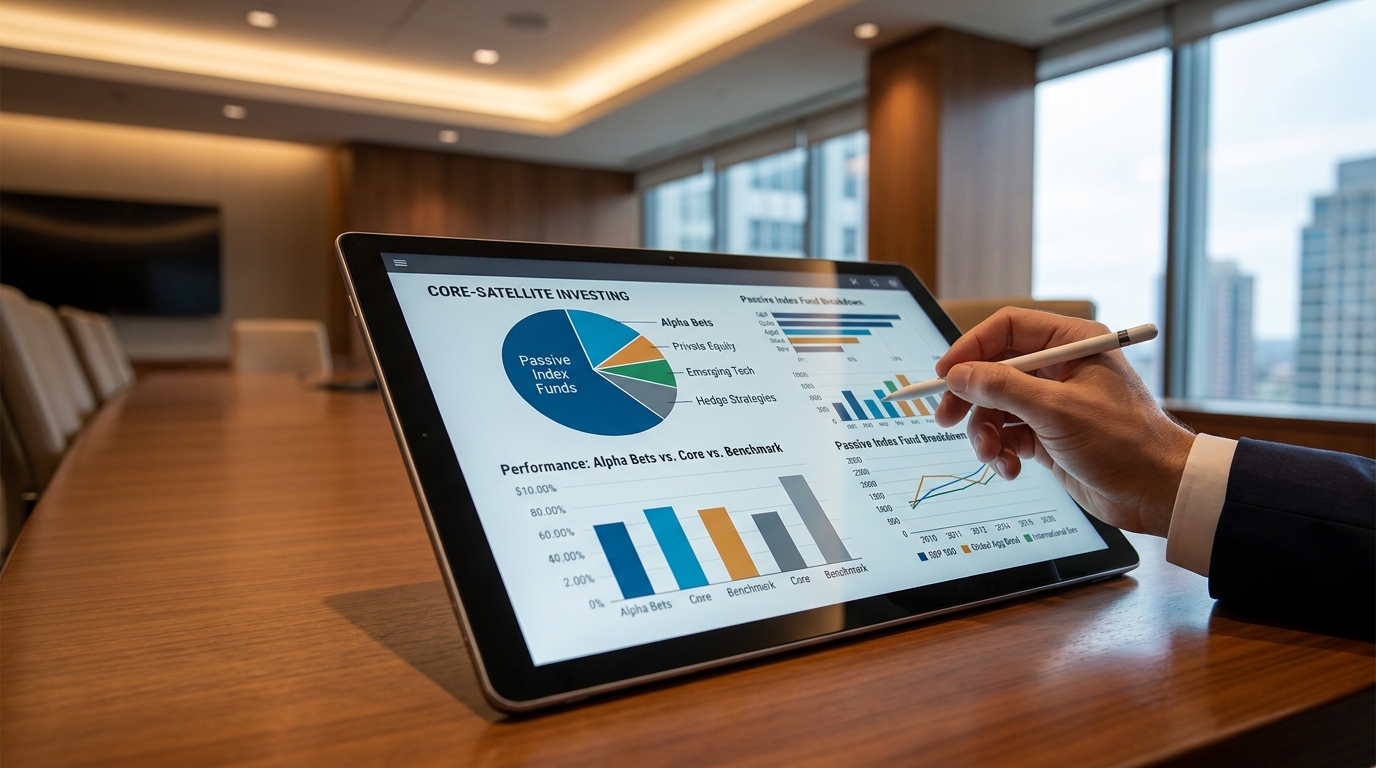
The mathematical premise of Core-Satellite investing hinges on bifurcating portfolio variance: capturing low-cost, capitalization-weighted beta across 60%–80% of invested capital to secure foundational market compounding, while ring-fencing 20%–40% for targeted alpha engines where active managerial skill, liquidity premiums, and structural market inefficiencies offer asymmetric risk-adjusted excess returns.
Executive Briefing: The Modern Asset Allocation Dilemma
For nearly four decades, private wealth management relied on a monolithic paradigm: the mechanical 60/40 equity-to-bond portfolio. When bond yields plummeted to historic lows and correlations between equities and sovereign fixed income turned positive during structural inflationary shocks, this classical equilibrium broke down. Investors found themselves trapped between two suboptimal extremes.
On one side stands the pure passive indexing purist. While market-capitalization weighting guarantees near-zero fee drag and zero manager selection risk, it forces investors to accept severe sector concentration—such as the top ten mega-cap tech stocks dictating over 30% of the S&P 500's volatility profile. On the opposing side, legacy retail active mutual funds continue their multi-decade record of systemic underperformance: S&P Dow Jones SPIVA scorecards consistently reveal that over 85% of active large-cap domestic equity managers underperform the broad market over a 15-year horizon after factoring in expense ratios and turnover friction.
Core-Satellite architecture resolves this ideological stalemate. It does not treat active and passive as mutually exclusive dogmas; rather, it categorizes asset classes based on market informational efficiency. Highly efficient markets are assigned to passive index cores, whereas asymmetric, niche, or mispriced corners of the global economy are delegated to concentrated satellites.
The Mathematical Foundation: Active Share, Tracking Error, & Information Ratio
Constructing a mathematically robust Core-Satellite portfolio requires institutional metrics that quantify whether excess volatility is adequately compensated by excess returns. Portfolio architects deploy three primary quantitative guardrails:
Measures the percentage of fund holdings that diverge from benchmark constituents. Satellites should possess Active Share exceeding 80% to eliminate closet indexing.
Standard deviation of excess returns relative to the benchmark. A portfolio with 75% core and 25% satellite maintains total portfolio TE under a conservative 2.5%.
Efficiency gauge evaluating whether an active manager generates excess return per unit of active risk. Target institutional satellites exhibit IR > 0.50.
Empirical testing demonstrates that capping active sleeves at 25%–30% allows investors to limit portfolio tracking error under 2.5%, insulating overall wealth against idiosyncratic active manager drawdowns while still capturing 70%+ of excess active returns.
Designing the Core Anchor (60%–80%): Low-Cost Market Beta
The Core anchor serves as the bedrock ballast of the investment strategy. Its mandate is unambiguous: capture total global economic productivity, reinvest dividend yields automatically, eradicate unnecessary cash drag, and maintain a blended expense ratio lower than 0.08%.
| Asset Sleeve | Benchmark Index | Exemplar Tickers | Expense Ratio | Target Weight |
|---|---|---|---|---|
| US Total Equities | CRSP US Total Market | VTI / ITOT / SCHB | 0.03% | 40% – 50% |
| Ex-US Developed & EM | FTSE Global All Cap ex US | VXUS / IXUS | 0.07% | 15% – 20% |
| Broad Sovereign / Agg Bond | Bloomberg US Aggregate Float | BND / AGG | 0.03% | 10% – 15% |
By pinning 70% of total assets into ultra-low-fee total-market indexes, the investor effectively immunizes their portfolio against style drifts, liquidity locks, and the catastrophic probability of individual firm insolvency.
Structuring Tactical Satellites (20%–40%): The Alpha Engines
Where the core provides non-negotiable solvency, satellites exist purely to exploit market asymmetries. Allocating capital to satellites requires strict intellectual honesty: each satellite must possess a validated structural premise, quantifiable factor exposure, or non-correlated cash flow profile.
Thematic Secular Disruption
Concentrated exposure to transformative macroeconomic shifts: AI hardware & software ecosystems, next-generation semiconductor fabrication, nuclear clean energy, and robotics. Satellites can tolerate deep volatility in exchange for non-linear power-law compounding.
Factor Tilts (Value & Quality)
Overweighting small-cap value, high return-on-invested-capital (ROIC) companies, and cross-asset momentum. Decades of academic asset pricing show systematic multi-factor tilts outperform market capitalization over rolling 10-year holding periods.
Private Credit & Mezzanine Debt
Direct corporate lending capturing illiquidity premiums and floating-rate yields (SOFR + 550-700 bps). Senior secured positioning shields capital while delivering uncorrelated quarterly income insulated from equity market volatility.
Commodities & Emerging Arbitrage
Physical gold reserves, industrial copper infrastructure plays, and single-country emerging market dislocations (e.g., Indian demographics or Mexican nearshoring). These assets exhibit near-zero correlation to US tech multiples.
Comparison Matrix: Core vs. Satellite Sleeves
The divergence between the core foundation and satellite components spans liquidity profile, tax impact, and behavioral discipline.
| Attribute | Core Anchor Sleeve | Tactical Satellite Sleeve |
|---|---|---|
| Primary Goal | Capture market beta, guarantee long-term wealth preservation | Generate idiosyncratic alpha, exploit pricing inefficiencies |
| Typical Allocation | 60% – 80% | 20% – 40% |
| Expense Ratio | 0.02% – 0.08% | 0.45% – 1.25% (or 1-and-10 in PE/Credit) |
| Active Share | 0.00% (Identical to benchmark) | 75% – 95% |
| Turnover & Tax Drag | Extremely low (<3% annual), ideal for taxable accounts | Moderate-to-high; prioritized in IRAs or 401(k) wrappers |
| Rebalancing Trigger | Strict calendar or wide tolerance bands (±7%) | Tight rebalancing bands (±3% to ±5%), profit-taking stop-losses |
Rebalancing Protocols and Risk Controls: The 5/25 Rule
Without strict rebalancing disciplines, a successful satellite holding can rapidly metastasize into an unintended portfolio hazard. For instance, an investor allocating 5% to an early AI chipmaker in 2022 might find that single satellite ballooning into 25% of their total net worth by 2024, inadvertently destroying the core's defensive risk properties.
The Institutional 5/25 Rebalancing Standard
Pioneered by institutional endowments, the 5/25 rule triggers an automatic portfolio rebalance whenever either of two conditions is met:
Applies to large asset classes (primarily the core). If your 50% US Core Equity target moves beyond 45% or 55%, rebalancing is mandatory regardless of market sentiment.
Applies to smaller satellite positions. For a satellite targeting 6% of portfolio value, 25% of 6% is 1.5%. If the position drifts below 4.5% or above 7.5%, profits must be skimmed and cycled back into the core.
Because satellites possess higher idiosyncratic volatility, they naturally produce distinct tax-loss harvesting windows during cyclical pullbacks. Institutional family offices deliberately trigger capital losses inside underperforming satellites to offset realized gains from harvested outperforming satellites, neutralizing net taxable burden while redeploying capital into adjacent correlated targets.
Real-World Case Studies: Allocation Blueprints
How does an institutional investor tailor the Core-Satellite balance according to investment horizon, liquidity requirements, and risk tolerance? Consider these two live archetypes:
The High-Net-Worth Preserver
Targeted for investors within 5 years of retirement seeking drawdown protection and steady quarterly cash flow while defending purchasing power against persistent inflation.
The Aggressive Compounder
Engineered for multi-decade horizon wealth accumulators maximizing capital growth, capable of stomaching transient market drawdowns in pursuit of outsized real returns.
Frequently Asked Questions
Critical technical questions addressed by TFT portfolio strategists regarding Core-Satellite implementation.
What is the single biggest operational mistake investors make with satellite sleeves?
The most prevalent blunder is "closet indexing" within the satellite allocation. Investors often buy active large-cap mutual funds that hold the exact same mega-cap stocks as their S&P 500 core, paying an unnecessary 0.85% expense ratio for duplicate exposure. Every satellite position must possess an Active Share of at least 80% relative to the core benchmark.
How should I locate Core vs. Satellite sleeves across taxable and retirement accounts?
Utilize asset location optimization: Keep your low-turnover, dividend-efficient Core broad index funds (such as VTI/VXUS) in standard taxable brokerage accounts where they generate minimal taxable events. High-turnover satellites (tactical momentum, private debt interval funds yielding ordinary income, and factor rebalancers) belong inside tax-advantaged accounts like Roth IRAs and traditional 401(k)s.
When should an underperforming satellite position be liquidated?
Establish an explicit investment thesis sunset date and stop-loss criteria before deploying capital. If the structural fundamental catalyst fails to materialize within 24 to 36 months, or if manager Active Share deteriorates below 70%, the position should be cut mercilessly. Avoid the sunk-cost fallacy: liquidate the satellite and sweep proceeds back into the Core anchor.
Does a Core-Satellite structure underperform during raging bull markets?
In speculative bull runs dominated by narrow mega-cap momentum (like the 2023 tech rally), a diversified Core-Satellite portfolio with non-correlated satellites (commodities, value tilts, private debt) may show mild benchmark lag. However, the architecture is engineered for superior Sharpe and Sortino ratios across full market cycles, outperforming significantly during sideways and bear markets.
What is the ideal number of satellite positions to hold simultaneously?
Institutional practice recommends between 2 to 4 satellite sleeves max. Holding more than 5 satellites inevitably results in "diworsification"—diluting your highest conviction insights, compounding transaction fees, and creating an unmanageable administrative burden that replicates an expensive index fund.
5 Core Decision Rules for Portfolio Construction
Never compromise the 60%–80% broad index core for speculative tactical ideas.
No individual satellite position should exceed 10% of total portfolio net asset value.
Satellites must deviate >80% from standard capitalization-weighted benchmarks.
Enforce mechanical profit-taking using systematic relative drift bands.
Liquidate satellites whose thesis fails without emotional attachment.